A Financial Assessment Based on Public Records
The Financial Condition of Pueblo County
Why I Prepared This Report
Financial stewardship is one of the most important responsibilities entrusted to local government. Every dollar collected from taxpayers should be managed carefully, invested prudently, and reported transparently.
As a candidate for Pueblo County Treasurer and as a citizen with a background in finance and management, I believed it was important to develop a better understanding of the County's financial condition. Rather than relying upon summaries or commentary, I reviewed the County's own published financial documents, including adopted budgets, audited Annual Comprehensive Financial Reports, and financing documents.
The purpose of this report is not to criticize individuals or assign responsibility for particular financial decisions. County finances reflect decisions and changing conditions accumulated over many years. Financial management is a shared responsibility.
Executive Summary
Overall Assessment
Pueblo County's financial position has become less resilient over the past several years.
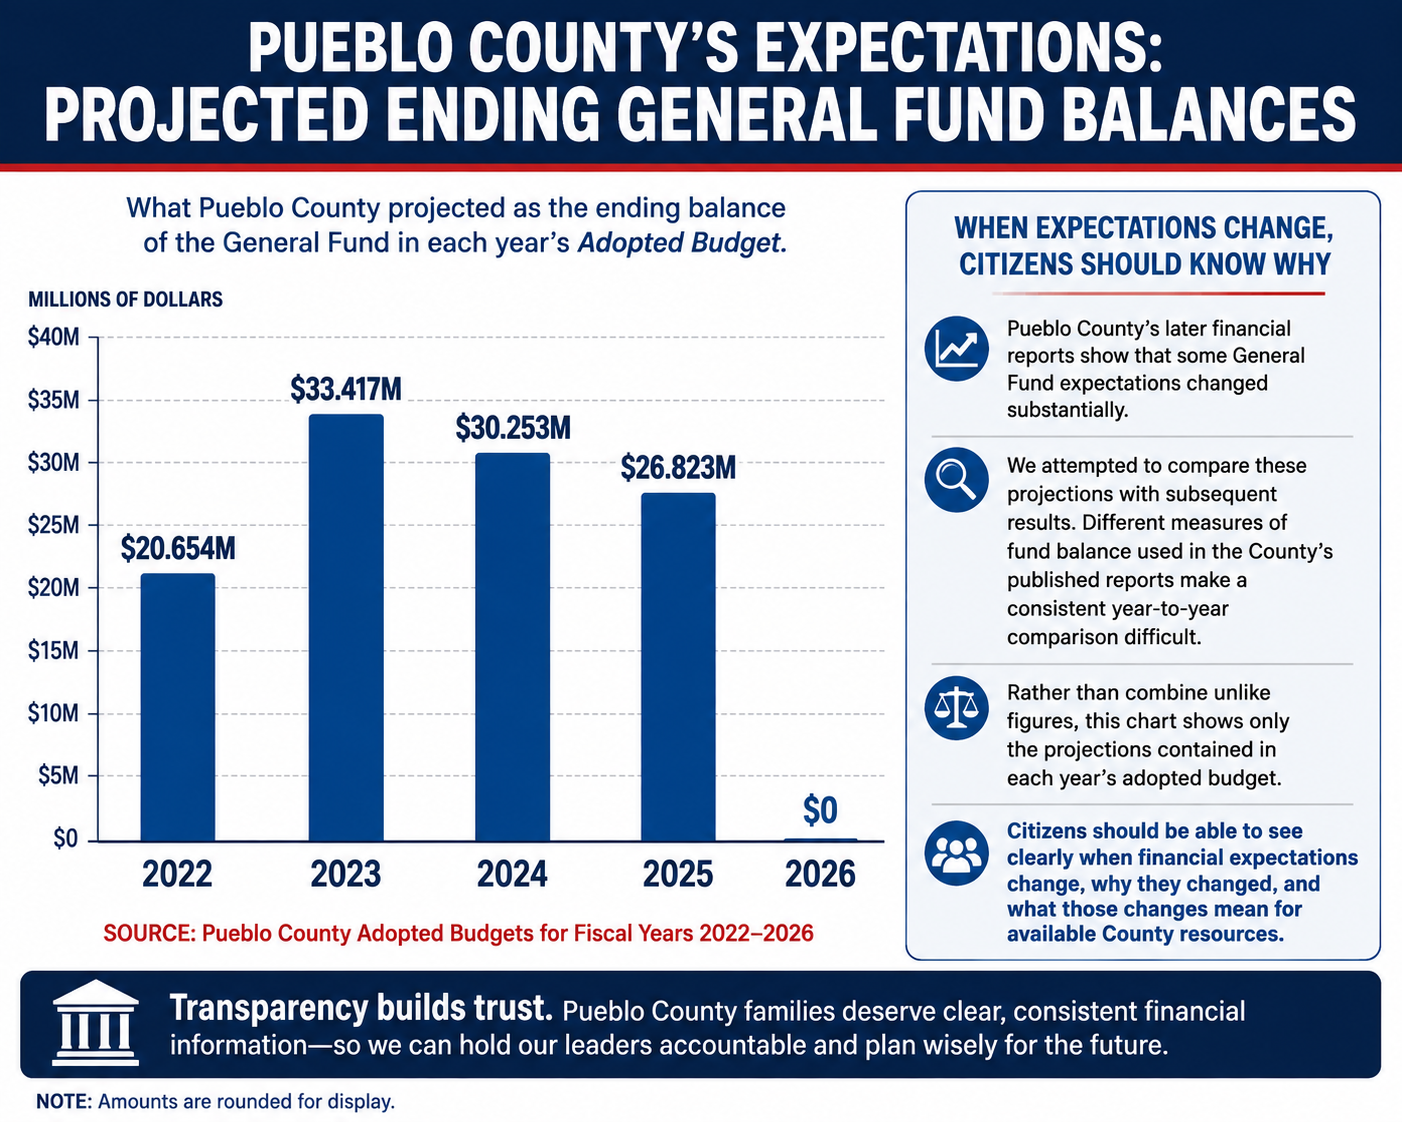
The County's adopted General Fund ending balance was approximately $20.7 million in the 2022 budget and $0 in the 2026 adopted budget. This change reflects the cumulative effect of several years of financial decisions and changing economic conditions rather than the actions of any single budget year.
At the same time, reduced liquidity, increasing long-term obligations, changing revenue trends, and the uncertain fiscal impact of the Aspen Acres Fire have narrowed the County's financial margin.
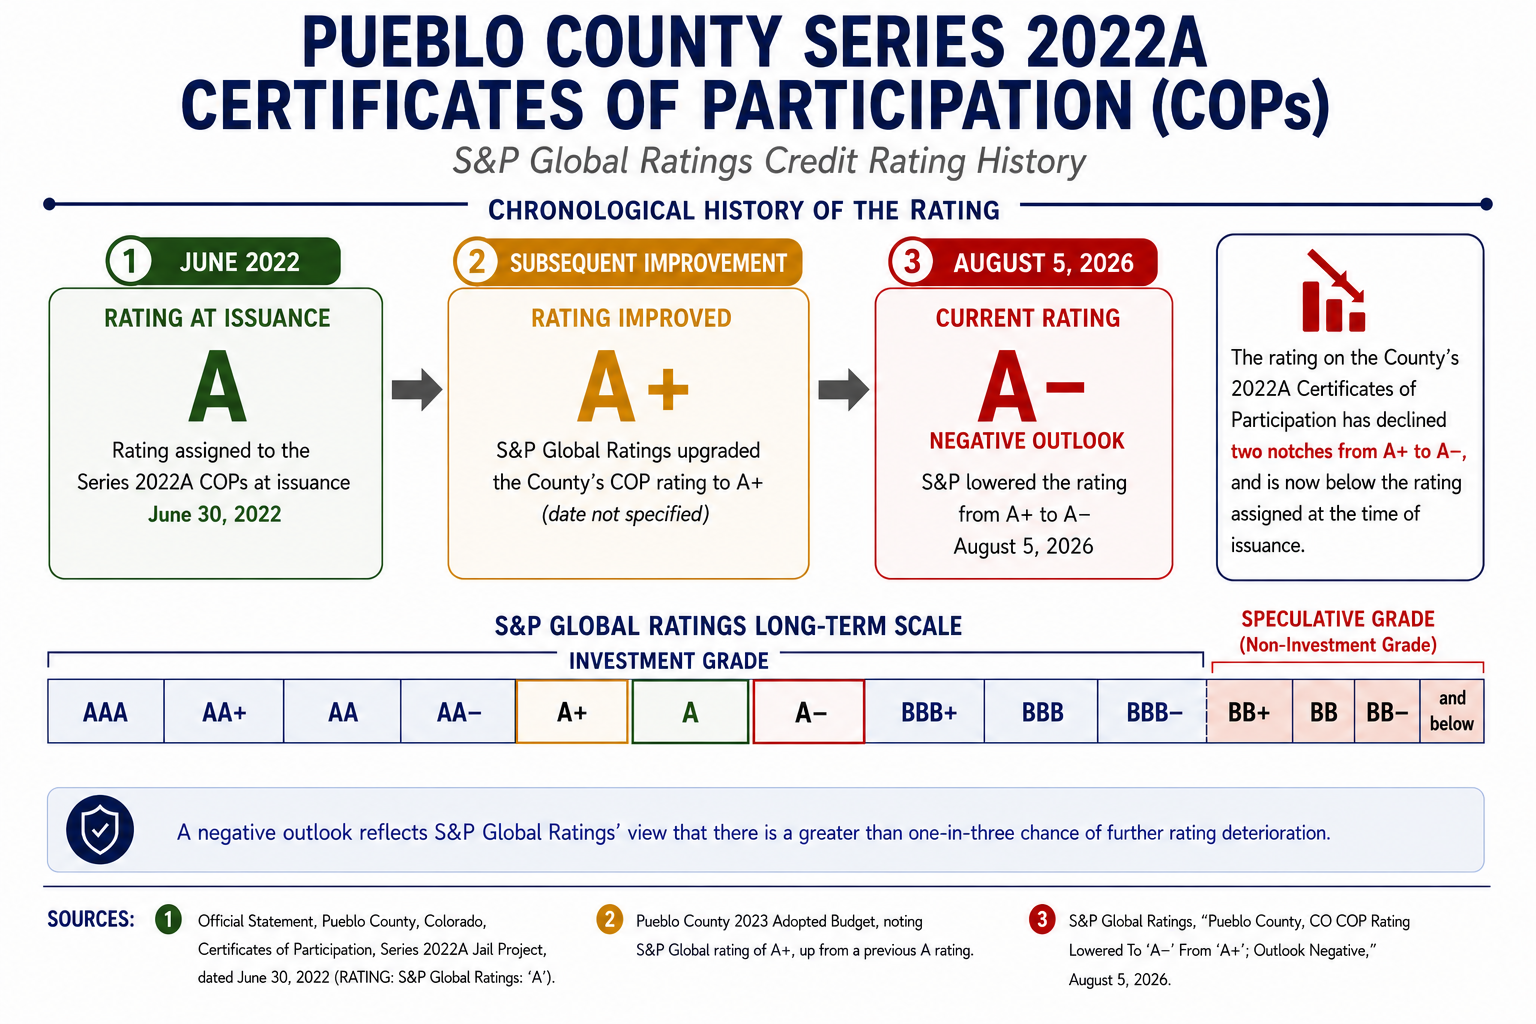
In August 2026, S&P Global Ratings lowered its rating on Pueblo County's Certificates of Participation from A+ to A- and assigned a negative outlook, citing weakening financial performance and reserves. This independent credit assessment is consistent with the declining financial resilience identified through the County records examined in this report.
The financial records reviewed do not indicate that Pueblo County is facing an immediate inability to meet its financial obligations. The County continues to receive unmodified opinions from its independent auditors and continues to provide essential public services.
However, the County has entered a period in which long-term financial stewardship has become increasingly important. A significant portion of the reduced financial capacity reflects planned capital investment. Those investments created valuable public assets, but they also increased long-term financial commitments while reducing the financial cushion available to respond to future challenges.
Two Indicators Worth Watching
Principal Findings
1. Financial Reporting Remains a Strength
Independent auditors continue to issue unmodified opinions on the County's financial statements. The County's published budgets, Annual Comprehensive Financial Reports, and financing documents provide an important foundation for evaluating its financial condition.
2. Financial Resilience Has Declined
The County's available financial cushion has diminished over the period reviewed. While a significant portion of this change reflects planned capital investment rather than unexpected operating losses, the County now has less capacity to absorb unexpected financial events than it did several years ago.
3. Long-Term Obligations Have Increased
Construction of the new detention facility and other capital improvements has increased the County's long-term financial commitments. The benefits of these investments will extend for decades, but so will the associated financial responsibilities.
4. Revenue Conditions Have Changed
Several recurring revenue sources remain stable, while others — notably excess marijuana sales tax revenues — have declined significantly. This places greater importance on long-term financial planning and prudent management of recurring expenditures.
5. The Aspen Acres Fire Introduces Significant Uncertainty
The County faces substantial but still unquantified financial consequences from the Aspen Acres Fire. Emergency response, infrastructure restoration, recovery efforts, potential reimbursements, and changes in future revenues may affect the County's financial condition for years to come.
Long-Term Financial Outlook
Pueblo County's financial future will depend less upon constructing new public facilities and more upon sustaining those already in place.
The financial records suggest that future success will depend upon:
- Rebuilding available reserves
- Preserving adequate liquidity
- Managing long-term debt responsibly
- Maintaining structural balance between recurring revenues and expenditures
- Adapting to changing revenue conditions
- Responding effectively to the long-term financial consequences of major emergencies
None of these issues individually indicates an immediate inability to meet the County's financial obligations. Collectively, they indicate that prudent long-term financial planning will become increasingly important during the coming decade.
What Should Come Next?
The complete report discusses seven observations and recommendations. Several principles consistently emerge from the financial records:
Rebuild Financial Flexibility
Rebuilding available reserves and preserving adequate liquidity would increase the County's ability to absorb revenue fluctuations, respond to emergencies, and manage unexpected expenditures.
Use Long-Term Forecasting
Multi-year financial forecasts should incorporate known obligations, recurring expenditures, capital requirements, reserve needs, and reasonable ranges of future revenue.
Maintain Structural Balance
Recurring expenditures should ultimately be supported by sustainable recurring revenues rather than continued reliance upon reserves or unusually strong temporary revenues.
Preserve Transparency
Timely, comprehensive, and comparable reporting is important both for effective financial management and for public accountability.
Conclusion
What do Pueblo County's own financial records tell us about its financial condition?
The answer is both reassuring in some respects and cautionary in others.
Pueblo County continues to meet its financial obligations and possesses substantial public assets. Its audited financial statements through 2024 received unmodified opinions from independent auditors, providing an important foundation for evaluating its historical financial condition.
At the same time, the County's financial resilience has declined. Long-term financial obligations have increased, certain revenue sources have weakened, and the County has less financial flexibility available to respond to changing economic conditions and unforeseen events.
The principal challenge identified by this assessment is not an immediate inability to meet current obligations, but the need to rebuild the financial capacity necessary to meet long-term commitments and respond effectively to future uncertainty.
Strengthening the County's financial capacity through careful planning, prudent financial stewardship, and responsible long-term decision-making will help ensure that Pueblo County remains prepared to meet both its long-term obligations and unforeseen events.
Read the Complete Assessment
The full report includes the supporting evidence, methodology, detailed financial observations, recommendations, acknowledgements, and principal sources used in preparing this assessment.
View Full Report